I remember watching some future vision videos like this Microsoft productivity future vision early in my career, and feeling inspired by that future. I’ve been excited by the possibility that our interaction with technology could fundamentally change and digital content could move beyond PCs and mobile phones and fit naturally into the real world. This is one of the main reasons I stayed in tech, and I’ve always wanted to stay close to the place building toward that vision.
AI agents are starting to generate content, connect tools, and complete tasks in the background, almost like those vision videos. But the interface is still mostly laptops and phones.
This gap is why XR feels interesting to me. It may expand what we can do with computers in daily life and work by letting AI and digital content fit into the real world in the right way. As we’ve recently seen new XR devices and developer platforms actively launching, I want to take a step back and look at what is happening in the XR market today.
Why XR feels interesting again
For over a decade, XR (spanning VR, AR, and MR) has been called the next computing platform after the smartphone. We’ve seen the booms including the metaverse hype, viral AR gaming like Pokemon Go, and wave after wave of “this is the year.”
It’s worth contrasting that with the wearables that did break through. The Apple Watch turned the smartwatch into a mainstream accessory, now on hundreds of millions of wrists. Smartwatches focus on a few clear jobs like notifications, quick payments, and health and fitness monitoring. These fit a concrete daily use and made the device fade into a habit.
Yet XR has never reached that kind of everyday use despite comparable investment. The VR headset was too heavy, too isolating, and used more as a session than a habit. The past few years brought a fresh round of serious attempts such as Apple’s Vision Pro, Meta’s Ray-Ban glasses, Google’s intelligent-eyewear announcements, Snap’s Specs, and a number of ambitious startups.
In 2026, something has changed about the shape of those attempts. The center of gravity in XR has shifted from VR/MR headsets to AI wearables. It has moved from a device you escape into, to a mobile device you take out into the world. And beneath the hardware, AI is driving a deeper shift in the interaction model from app-centric to intent-centric.
On a phone, you take it out of your pocket, unlock it, find the right app, open it, and then do what you want. The app grid is a menu of tools, and you are the one picking between them. On glasses there is no room for an app grid, so the model flips. You say what you want (”translate this menu,” “remind me to call her tonight,” “what am I looking at?”), and an AI figures out which tools to use and does it. The unit of interaction stops being the app and becomes the intent.
This matters because usability has always been one of XR’s core blockers. Smart glasses and headsets have no good physical input like a keyboard. For years the fallback was voice, and voice did not really work well, because recognition was unreliable and the system could not interpret what you actually meant. Modern AI fixes that problem. Multimodal models process voice, vision, and context simultaneously, and realtime APIs have collapsed the latency that made earlier voice interfaces feel broken. The system can now understand what you mean and act on it.
XR device category
XR devices are often discussed as a single category, but in practice they serve very different needs. Being immersed in a virtual world has little in common with glancing at a heads-up notification, and neither looks much like asking your glasses a question while walking down the street. The use cases and the occasions differ for each type of device.
- VR/MR headset: Immersive experiences through a head-mounted display, offering high presence and, in mixed-reality mode, the ability to overlay virtual content on a camera view of the real world. Because of weight, form factor, and cost, adoption stays limited to specific use cases like gaming and fitness, rather than everyday wear. Key products: Meta Quest, Samsung Galaxy XR, Apple Vision Pro.
- Tethered Glass: Glasses connected to an external compute device (a phone, laptop, or pocket unit) that offloads processing so the optics stay lightweight without sacrificing performance. With devices like Xreal’s Project Aura, the category is expected to move beyond accessory status toward a spatial computing platform. Key products: Xreal One / One Pro, and the upcoming Xreal Project Aura (Android XR).
- Smart glasses with a display: Lightweight glasses that layer heads-up information and digital content onto the real world, aiming for an always-on, everyday form factor. The category still faces real challenges in design, price, and use cases. Meta has pushed it furthest with the Ray-Ban Display, and startups like Even Realities are trying leaner, versions that look more like ordinary glasses without a camera. This is all very early, and it is not yet clear how it’ll reach the mass market. Key products: Meta Ray-Ban Display, Snap Specs, Even Realities G1/G2, Google/Samsung display glasses.
- Smart glasses without a display: Glasses with a camera, microphone, and speaker but no screen, focused on voice-first interaction. They capture what the user sees and feed that context to an AI for conversation and assistance. They have nearly reached the design and form factor where people actually want to wear them as everyday glasses. Ray-Ban Meta is the standout with strong consumer traction, input through both vision and voice, and AI that turns that input into action. Key products: Ray-Ban Meta Gen 2, Oakley Meta, Google/Samsung audio glasses.
Market size
The clearest signal of the shift is in the numbers. According to IDC’s June 2026 analysis, display-less smart glasses (the Ray-Ban Meta category) grew 167% year over year in Q1 2026, reaching roughly 2.25 million units in a single quarter. For perspective, the entire category shipped about 2.7 million units in all of 2024. It now ships nearly that much every three months.
It is not just display-less glasses. Smart glasses with display grew 86% year over year in the same quarter and have become the main act of the XR market.
Looking ahead, IDC forecasts the display-less smart glasses will reach about 13.6 million units in full-year 2026 and 27.3 million by 2030, an 18.9% CAGR. Display glasses are forecast to grow even faster at nearly 42% a year and pass VR/MR headsets in volume. These forecasts suggest the market is consolidating around glasses.
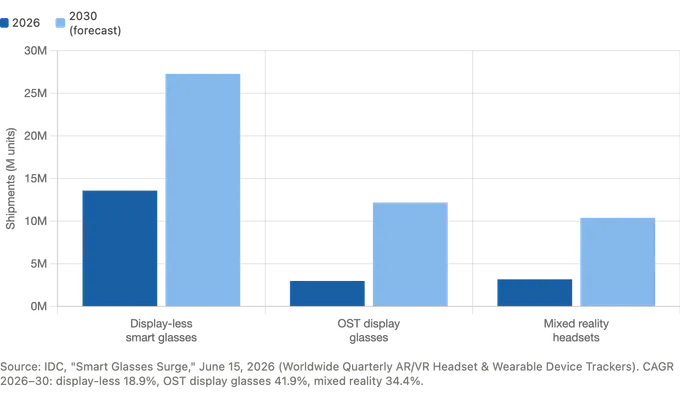
For now, Meta owns most of the smart glass market with 69.2% share in Q1 2026. That lead is about to be tested. Google’s Android XR intelligent eyewear launches in fall 2026 (audio-first, with a display version following in 2027), and Apple is reportedly preparing its own display-less AI glasses for 2027.
AI is what finally made XR devices useful
Across the whole spectrum, AI is becoming the layer that makes XR devices do things rather than just display them. Apple, Meta, Samsung, and Google are all building assistants (Siri, Meta AI, Gemini) into their devices as a primary way to navigate and create. Users can now instruct devices in natural language, so voice and conversation replace the keyboard and touchscreen these form factors never had. XR devices also increasingly act as an input layer for AI, where cameras and microphones feed what the user sees and hears to an AI agent that interprets the context and responds or completes the task.
Key players in XR ecosystem
The big platform players, Meta, Google, Apple, and Snap, are each racing to build not just devices but the developer tools and ecosystems around them. Here is where each stands.
Meta: From Oculus to Quest to a costly metaverse bet, Meta spent a decade trying to own immersive computing, and is now shifting decisively toward the smart glasses category. Meta ships two display-less lines, Ray-Ban Meta (Gen 2) and Oakley Meta (the volume driver, about $300 to $400), plus the Ray-Ban Display ($799), which adds an in-lens display and a wristband for silent, touch-free control. Meta opened the Device Access Toolkit (DAT) in developer preview in 2025, and extended it to the Ray-Ban Display screen in 2026. Further out, Meta is reportedly still developing true mixed-reality glasses (the “Phoenix” project, now pushed toward 2027) and a rebooted Quest, but the near-term resources clearly favor wearables over headsets.
Google: Google is back in this category with Android XR, an OS built with Samsung and Qualcomm, with Gemini as the interface and a developer SDK for building across the platform. Its 2026 lineup spans three tiers: the Samsung Galaxy XR headset ($1,799), Xreal’s Project Aura tethered glasses, and intelligent eyewear announced at I/O 2026 in two versions, audio-only and display, co-designed with eyewear brands. Google clearly learned from Google Glass. The lesson from 2013 was that a face computer fails if people do not want to wear it in public, which is why Google is now partnering with eyewear brands like Warby Parker and Gentle Monster to make glasses that fit into daily life. Its other advantage is the Android developer ecosystem, which is larger than Meta’s. If Google can bring those developers and the apps and services people already use on Android into glasses, its products can be more useful out of the gate.
Apple: Apple’s Vision Pro proved the ceiling but not the market. Reportedly shipments have fallen since its launch year in 2024, when they were estimated at around 400,000 units. Apple shipped an M5-refreshed Vision Pro in late 2025, but a reported June 2026 roadmap overhaul (under incoming CEO John Ternus) scaled the Vision Pro line back and pivoted toward glasses. According to analysts, the current timeline is display-less AI glasses around late 2027, followed by display-equipped AR glasses with optical waveguides no earlier than 2029, while a cheaper, lighter “Vision Air” headset has slipped to 2028 or 2029. Apple is also overhauling Siri (with help announced at WWDC 2026) to be ready for the glasses era. When Apple does arrive, the expectation is that it ships a more refined and more complete product than whatever Meta, Google, or Snap have on the market by then. Its developer base gives it a real head start in building that ecosystem on glasses: a huge developer base across iOS and macOS, a growing one on visionOS, and the tightest hardware-software-services loop in the industry.
Snap: Snap has bet on eyewear since Spectacles in 2016, iterating quietly through generations. At AWE on June 16, 2026, it revealed Specs - standalone see-through AR glasses, shipping fall 2026 at $2,195, with over $3.5B invested. A decade of iteration has also built it a real developer ecosystem. Over 400,000 developers have built with Lens Studio, now extended with agentic dev tools. Specs are not really competing with screenless AI glasses alone. They sit closer to a new category between smart glasses and headsets, trying to bring some of the immersive, high-quality spatial experience of devices like Vision Pro or Galaxy XR into an eyewear form factor. That difference matters for usage. I could imagine wearing something like this on a plane or in a coffee shop, places where I would never want to put on a VR headset. The big open question is whether the comfort, weight, battery life, and everyday utility are good enough for that promise to hold up in real use.
Beyond the platform players, a layer of specialists is shaping the category. Even Realities (G1/G2) makes minimalist, prescription-friendly display glasses with no camera, the deliberate approach of glasses first with specific use cases like live translation. Behind the scenes sit the infrastructure players: Qualcomm (Snapdragon XR powers nearly every non-Apple device), Nvidia (the rendering and digital-twin backbone), and EssilorLuxottica (the eyewear manufacturing, brand, and retail muscle behind Ray-Ban Meta).
Challenges ahead
Despite the momentum, several real obstacles stand between today’s glasses and genuine mass adoption.
Privacy. Alway-son camera on your face is a very different privacy proposition than a phone. Meta has already drawn criticism here. Reportedly Meta stored and used photos taken by AI glasses for AI training and planned to develop a facial-recognition feature. Privacy is one of the biggest blocker to mass adoption. The makers and developers who treat privacy as a first-class design priority will be the ones who earn lasting trust.
Design. Smart glasses have to look like glasses people would wear anyway, regular frames or sunglasses, not a bulky eyewear computer. This is exactly why the tech companies now partner with eyewear brands (Meta with Ray-Ban and Oakley, Google with Warby Parker and Gentle Monster). The device has to pass as fashion before it passes as tech. For display-less glasses this threshold is nearly crossed. Adding a display still brings back weight, bulk, battery, heat, and complexity.
Price. Smart glasses and VR headsets are still an additional computer purchase, unless people start to see them as a replacement for regular glasses (like Apple watch did for the watch category). At about $300, Ray-Ban Meta sits where that mental model lives, and it is the only breakout hit. Most of XR devices like Snap Specs and Galaxy XR headset are fighting against that anchor.
Ecosystem. People need real reasons to use these every day, with useful applications and use cases beyond the novelty. The developer ecosystems are young (Meta’s toolkit and Android XR just opened), and the use cases are still emerging. Hardware may cross the fashion and price thresholds, but the category will still stall if there is nothing compelling to do all day.
Summary
Across the four categories the clearest momentum is in AI glasses. Design is closing in on normal eyewear, price points are approaching mass-market territory, and AI has finally given them a genuine reason to exist. Whether it is voice-based AI glasses or the emerging display glasses, the core proposition is a lightweight, always-on device that sees what you see, hears what you hear, and acts on your behalf.
I wear glasses every day (I don’t use contact lenses), so I need something on my face anyway, and I’ll happily wear a pair regularly as long as it fits well and doesn’t feel awkward. I feel the glasses have finally gotten small and light enough to actually want to wear, and AI has made them genuinely useful. Combine those two and you start to expand what is possible in how humans interact with technology, and what we can do with a computer at all.
I just got a pair of Ray-Ban Meta (Gen 2) and am using them daily. I also plan to build some demo apps with Meta’s wearable device access kit (DAT). I’ll share hands-on findings and insights in future posts.